Curious about how much auto insurance is going to dent your wallet in Massachusetts? You’re not alone! Navigating the world of auto insurance can feel like steering through a labyrinth with no clear exit. But fear not, because we’re here to break it all down for you.
In this guide, inspired by the authoritative style of Backlinko, we’ll explore everything you need to know about auto insurance in Massachusetts—from the basics of mandatory coverage to the factors that influence your premium rates. Get ready to become an informed driver who knows exactly what you’re paying for!
Understanding Auto Insurance Basics in Massachusetts
Did you know the average cost of auto insurance in Massachusetts is around $1,460 a year? It’s crucial to know exactly what you’re paying for and why.
Auto insurance in Massachusetts isn’t just a suggestion. It’s a legal requirement. You need to have a firm grasp on the basics to ensure you’re covered correctly and not just throwing money out the window.
Essential Components of Auto Insurance Policies in Massachusetts
Every auto insurance policy in Massachusetts includes a few key components. Liability coverage is a big one. It covers you if you’re at fault in an accident and pays for the other party’s injuries or property damage. Then there’s personal injury protection (PIP), which helps with your own medical expenses regardless of who caused the accident.
And don’t forget uninsured motorist coverage. This kicks in if you’re hit by someone who doesn’t have insurance.
“Uninsured motorist coverage safeguards your wallet when the other driver can’t.”
These components are non-negotiable in Massachusetts.
Mandatory Coverage Requirements for Drivers in Massachusetts
Before hitting the road, you need to check off a few boxes. Massachusetts requires certain minimum levels of coverage for every driver.
- You must have $20,000 per person/$40,000 per accident in bodily injury liability.
- There’s a demand for $5,000 for property damage liability.
- Personal Injury Protection should be at least $8,000.
- And don’t skip on uninsured motorist coverage of $20,000 per person/$40,000 per accident.
Here is the deal: If you want peace of mind and to avoid hefty fines or lawsuits, make sure these boxes are ticked off on your insurance policy.
Factors Influencing Auto Insurance Rates

Did you know that your auto insurance rate in Massachusetts might be higher just because of your zip code? Yes, it’s true! The state is known for its diverse urban and rural areas, and that diversity doesn’t just affect your lifestyle—it impacts your insurance premiums too.
But what exactly determines how much you pay? Let’s break down the key factors that play a role in shaping your insurance costs.
Age and Driving Experience
Your age and how long you’ve been behind the wheel are big players in this game. Younger drivers, particularly those under 25, usually pay more because they’re deemed as higher-risk. On the flip side, those with decades of driving experience often enjoy lower rates. Here is the deal: insurance companies see age as a measure of risk.
Vehicle Type and Usage
Not all cars are created equal in the eyes of insurers. High-performance sports cars or luxury vehicles? Expect to shell out more. On the other hand, if you own a safe, reliable sedan, your bank account might breathe easier. Why? Vehicle type affects repair costs and accident likelihood.
Driving History and Claims
A clean driving record can be your ticket to lower premiums. But if you’ve had a few fender benders or speeding tickets, brace yourself. Insurers view a spotty driving history as a red flag, leading to higher rates. The more claims you’ve made, the more you’re likely to pay—simple as that.
Comparison of Key Factors
Let’s take a look at how these factors stack up against each other and influence your premiums.
| Factor | Impact on Premiums |
|---|---|
| Age | High if under 25, decreases with age |
| Vehicle Type | Higher for sports and luxury cars |
| Driving History | Clean record lowers rates, violations increase them |
Pro Tip: Maintain a clean driving record and consider low-risk vehicles to keep your premiums in check.
Average Cost of Auto Insurance in Massachusetts
Ever wondered how much you’re shelling out for auto insurance compared to your neighbors? Well, brace yourself because Massachusetts drivers pay more than most Americans for their auto insurance. But don’t worry, I’m here to break down the average costs for you.
Massachusetts auto insurance rates are influenced by a host of factors, but let’s cut to the chase. The average cost in Massachusetts is approximately $1,460 per year. That’s a bit higher than the national average of $1,321. Why is that? The high population density and vehicle theft rates in cities like Boston drive up premiums.
Comparison of Premium Rates Among Major Cities
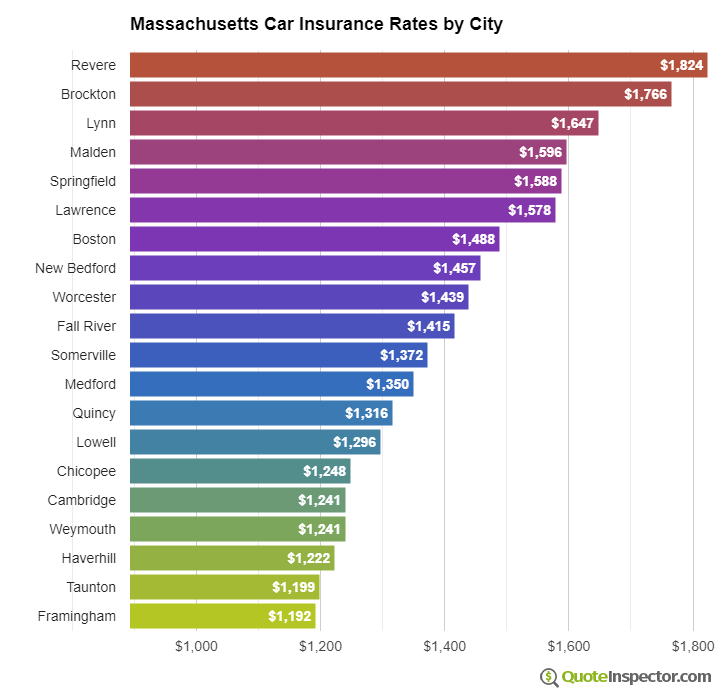
Diving deeper, rates fluctuate significantly depending on where you live in Massachusetts. Here’s a handy table comparing premium rates across major cities:
| City | Average Annual Premium |
|---|---|
| Boston | $1,752 |
| Worcester | $1,483 |
| Springfield | $1,419 |
| Cambridge | $1,560 |
| Lowell | $1,523 |
It’s pretty clear from the table: living in Boston could cost you over $300 more per year compared to Springfield. So what’s the takeaway? Choose your city wisely because it can hit your wallet hard.
How Massachusetts Averages Compare Nationally
Now, let’s zoom out and see how Massachusetts stacks up against the rest of the country. The bad news? Massachusetts is one of the pricier states. BUT, it’s not all doom and gloom. The state boasts robust coverage requirements which can be a lifesaver in case of an accident.
Pro Tip: Always shop around. Rates can differ drastically between insurers, even for the same coverage!
So here’s the deal: while Massachusetts might be above the national average, the peace of mind you get with comprehensive coverage could be worth every penny. Now that you know the numbers, you’re better equipped to make smart insurance choices.
Discounts and Savings Opportunities
Want to slash your auto insurance premiums in Massachusetts? You’re in luck! There are tons of discounts available that can save you big bucks if you know where to look.
Insurance companies love offering discounts. Why? Because it incentivizes safe driving and fosters customer loyalty. But here is the deal: not everyone knows how to tap into these savings. Let’s dive into the discounts you should definitely consider.
Common Discounts Available in Massachusetts
Unlocking these discounts can be easier than you think. Here’s a quick rundown:
- Good Driver Discount: Are you a responsible driver with a clean record? Many insurers offer reduced rates for drivers who have stayed accident-free for a certain period.
- Multi-Policy Discount: Bundle your auto insurance with homeowners or renters insurance. Insurers love this and usually reward you with lower premiums.
- Student Discount: If you’re a young driver with good grades, you’re in for a treat. Many companies provide discounts for students maintaining a ‘B’ average or better.
- Pay-in-Full Discount: Paying your premium upfront can sometimes knock off a nice chunk of the cost. It’s a win-win for both you and the insurer.
- Safety Features Discount: Does your car have anti-lock brakes, airbags, or an anti-theft system? These features don’t just keep you safe—they can also lower your insurance rates.
Pro Tip: Always ask about discounts when shopping for insurance. Even if they’re not advertised, you might qualify for savings you didn’t know about!
Strategies to Maximize Savings
Here are some strategies to help you maximize your auto insurance savings:
- Shop Around: Different insurers offer different rates. Get quotes from multiple companies to ensure you’re getting the best deal.
- Review Your Coverage Annually: As your situation changes, so might your needs. Ensure your coverage aligns with your current life stage and risk tolerance.
- Increase Your Deductible: Opting for a higher deductible can lower your premium. Just ensure you have enough savings to cover it in the event of a claim.
- Maintain a Good Credit Score: Believe it or not, your credit score can influence your insurance rates. Keep your credit in check to help secure lower premiums.
- Utilize Telematics: Some insurers offer usage-based insurance programs. By installing a small device in your car, you can prove your safe driving habits and possibly earn discounts.
Comparing Insurance Providers
Looking for the best auto insurance in Massachusetts? You’re not alone. The market is packed with options, but not all providers are created equal.
Believe it or not, choosing the right insurance can save you hundreds each year. BUT here’s the deal: it’s not just about price. You need to understand what each provider offers.
Key Features to Compare
First, look at coverage options. Some insurers offer more comprehensive coverage, which can provide peace of mind in case of an accident. Make sure to compare what’s included and any add-ons.
Next, evaluate customer service. Online reviews and ratings can give you insights into how an insurer treats its clients. A provider might have the best rates, but if they’re impossible to reach during claims, that’s a red flag.
Price vs. Value: Finding the Right Balance
Keep an eye on the deductibles. A lower premium might come with a higher deductible, which means you’ll pay more out-of-pocket in case of a claim. Weigh this against the overall cost to find your sweet spot.
Pro Tip: Don’t just focus on premiums. Always check the fine print for exclusions and limitations.
Finally, consider discounts. Many providers offer discounts for safe drivers, bundling policies, or even for being a loyal customer. These can add up to significant savings!
Evaluating Financial Stability
It’s crucial to check the insurer’s financial strength. You want a company that can pay out claims without hassle. Look for ratings from agencies like A.M. Best or Moody’s.
Here’s a simple way to compare:
| Provider | Coverage Options | Customer Service Rating | Price | Discounts |
|---|---|---|---|---|
| Provider A | Basic, Comprehensive | 4.5/5 | $$ | Safe Driver, Multi-Policy |
| Provider B | Comprehensive, Premium | 4.7/5 | $$$ | Loyalty, Student |
Step #1: List your priorities. Step #2: Match providers to these criteria. And you’re set!
Recent Trends in Massachusetts Auto Insurance
Did you know that Massachusetts auto insurance rates have seen significant shifts recently? These changes could impact how much you’ll pay for coverage.
From regulatory shifts to new insurance products, several factors are shaking up the Massachusetts auto insurance landscape. Here’s what you need to know to stay ahead of the curve.
Regulatory Changes in Massachusetts Auto Insurance
The Massachusetts Division of Insurance has introduced new regulations that aim to increase transparency and competition among providers. These changes mean insurers are now required to provide more detailed rate justifications.
This regulatory shift could lead to more competitive pricing, but it also means insurers might adjust rates to comply. Stay alert for new pricing models that might either benefit or challenge your current budget.
Innovative Insurance Products
Insurance companies in Massachusetts are rolling out usage-based insurance products. These policies adjust rates based on your driving habits monitored through telematics devices.
This could be a game-changer. If you’re a safe driver, you might save big. BUT, if you frequently hit the brakes hard or clock high mileage, be prepared for potential rate hikes.
According to Jane Doe, an expert analyst at Insurance Trends Inc., “Massachusetts is at the forefront of adopting innovative insurance solutions, which may set a precedent for other states.”
Impact of Trends on Future Rates
With these recent trends, it’s crucial to keep an eye on how they influence future rates. As insurers adapt, you might see fluctuations in premiums that could either save you money or lead to increased costs.
Here’s the deal: Stay informed and be ready to switch providers if necessary to get the best rates. It’s all about maximizing your savings while ensuring adequate coverage.
Final Summary
Wrapping up, understanding the ins and outs of auto insurance in Massachusetts doesn’t have to be an uphill battle. With these insights and tips at your fingertips, you’re now equipped to make smarter decisions and potentially save on your premiums. Remember, the road to affordable auto insurance starts with knowledge and a bit of savvy shopping.
Frequently Asked Questions
What are the essential components of auto insurance policies in Massachusetts?
Auto insurance in Massachusetts typically includes liability coverage, personal injury protection, uninsured motorist coverage, and optional collision and comprehensive coverage.
What mandatory coverages are required for drivers in Massachusetts?
Massachusetts requires drivers to have bodily injury liability, property damage liability, personal injury protection, and uninsured motorist coverage.
How do factors like age and driving history affect insurance rates?
Insurance rates can vary significantly based on age, with younger drivers often facing higher premiums. A clean driving history can lead to lower rates, while accidents or violations may increase costs.
What is the average cost of auto insurance in Massachusetts?
On average, drivers in Massachusetts pay around $1,200 to $1,500 annually for auto insurance, though this can vary based on individual profiles and locations.
How can Massachusetts residents save on auto insurance?
Residents can save by taking advantage of discounts for good driving, bundling policies, or installing safety features in their vehicles.
What should I look for when comparing insurance providers?
Consider factors like coverage options, customer service, financial stability, and customer reviews to find the best provider for your needs.
Are there any recent trends affecting auto insurance rates in Massachusetts?
Recent trends include regulatory changes and new insurance products, which could impact future rates and options available to consumers.