Tag: insurance benefits

  • Unlocking the Benefits of John Hancock Gold Travel Insurance

    Are you looking for a travel insurance plan that offers comprehensive coverage and peace of mind? Look no further than John Hancock Gold Travel Insurance. This plan is designed for travelers who want to explore the world without worrying about unexpected events that could disrupt their journey. From lost luggage to medical emergencies, this insurance has you covered.

    Backed by a trusted name in the insurance industry, John Hancock Gold Travel Insurance provides a robust array of benefits tailored to meet the diverse needs of modern travelers. Whether you’re flying across the globe or embarking on a weekend getaway, this plan ensures you’re protected every step of the way. Let’s dive into the details of what makes this insurance a must-have for savvy travelers.

    Overview of John Hancock Gold Travel Insurance

    Did you know that 1 in 5 travelers face unexpected disruptions? That’s why having comprehensive travel insurance is crucial!

    John Hancock Gold Travel Insurance offers you peace of mind with a range of benefits tailored to cover your travel needs. From trip cancellations to medical emergencies, this plan ensures you’re protected even before you pack your bags.

    Why Choose John Hancock Gold Travel Insurance

    Travel insurance is not just about covering risks; it’s about traveling with confidence. The John Hancock Gold plan is designed to offer you extensive benefits, including trip cancellation, medical expenses, and lost luggage coverage. Plus, it comes with a 24/7 assistance service to help you navigate any travel hiccups.

    Here’s the deal: the policy covers you against almost any travel-related mishap. Whether it’s a hurricane disrupting your flight or an unexpected illness, John Hancock has got you covered. BUT, it’s important to understand every layer of coverage to maximize your benefits.

    Coverage Options Available

    The Gold Travel Insurance plan doesn’t just stop at the basics. It expands to cover:

    • Trip Interruption – Reimburses unused trip costs and additional transportation expenses.
    • Emergency Medical and Dental – Covers expenses if you fall ill or get injured while traveling.
    • Baggage Loss – Provides compensation for lost or damaged belongings.
    • Travel Delay – Offers reimbursement for meals, accommodation, and transportation during delays.

    Pro Tip: Always read the fine print to understand what’s truly covered and any exclusions that may apply.

    How to Acquire John Hancock Gold Travel Insurance

    Getting your hands on a policy is easier than you think. Here’s a quick step-by-step:

    1. Visit the official John Hancock website and navigate to the travel insurance section.
    2. Choose the Gold Travel Insurance plan by comparing it with other options available.
    3. Fill out your travel details and personal information to get your quote.
    4. Review the policy terms carefully and make your purchase online.
    5. Receive your insurance documents via email immediately after purchase.

    The process is streamlined to ensure you spend more time planning your trip rather than worrying about the paperwork. BUT, always double-check your details before finalizing the purchase.

    Key Features and Benefits of the Insurance Plan

    To make it clearer, here’s a snapshot of the key features:

    Feature Benefit
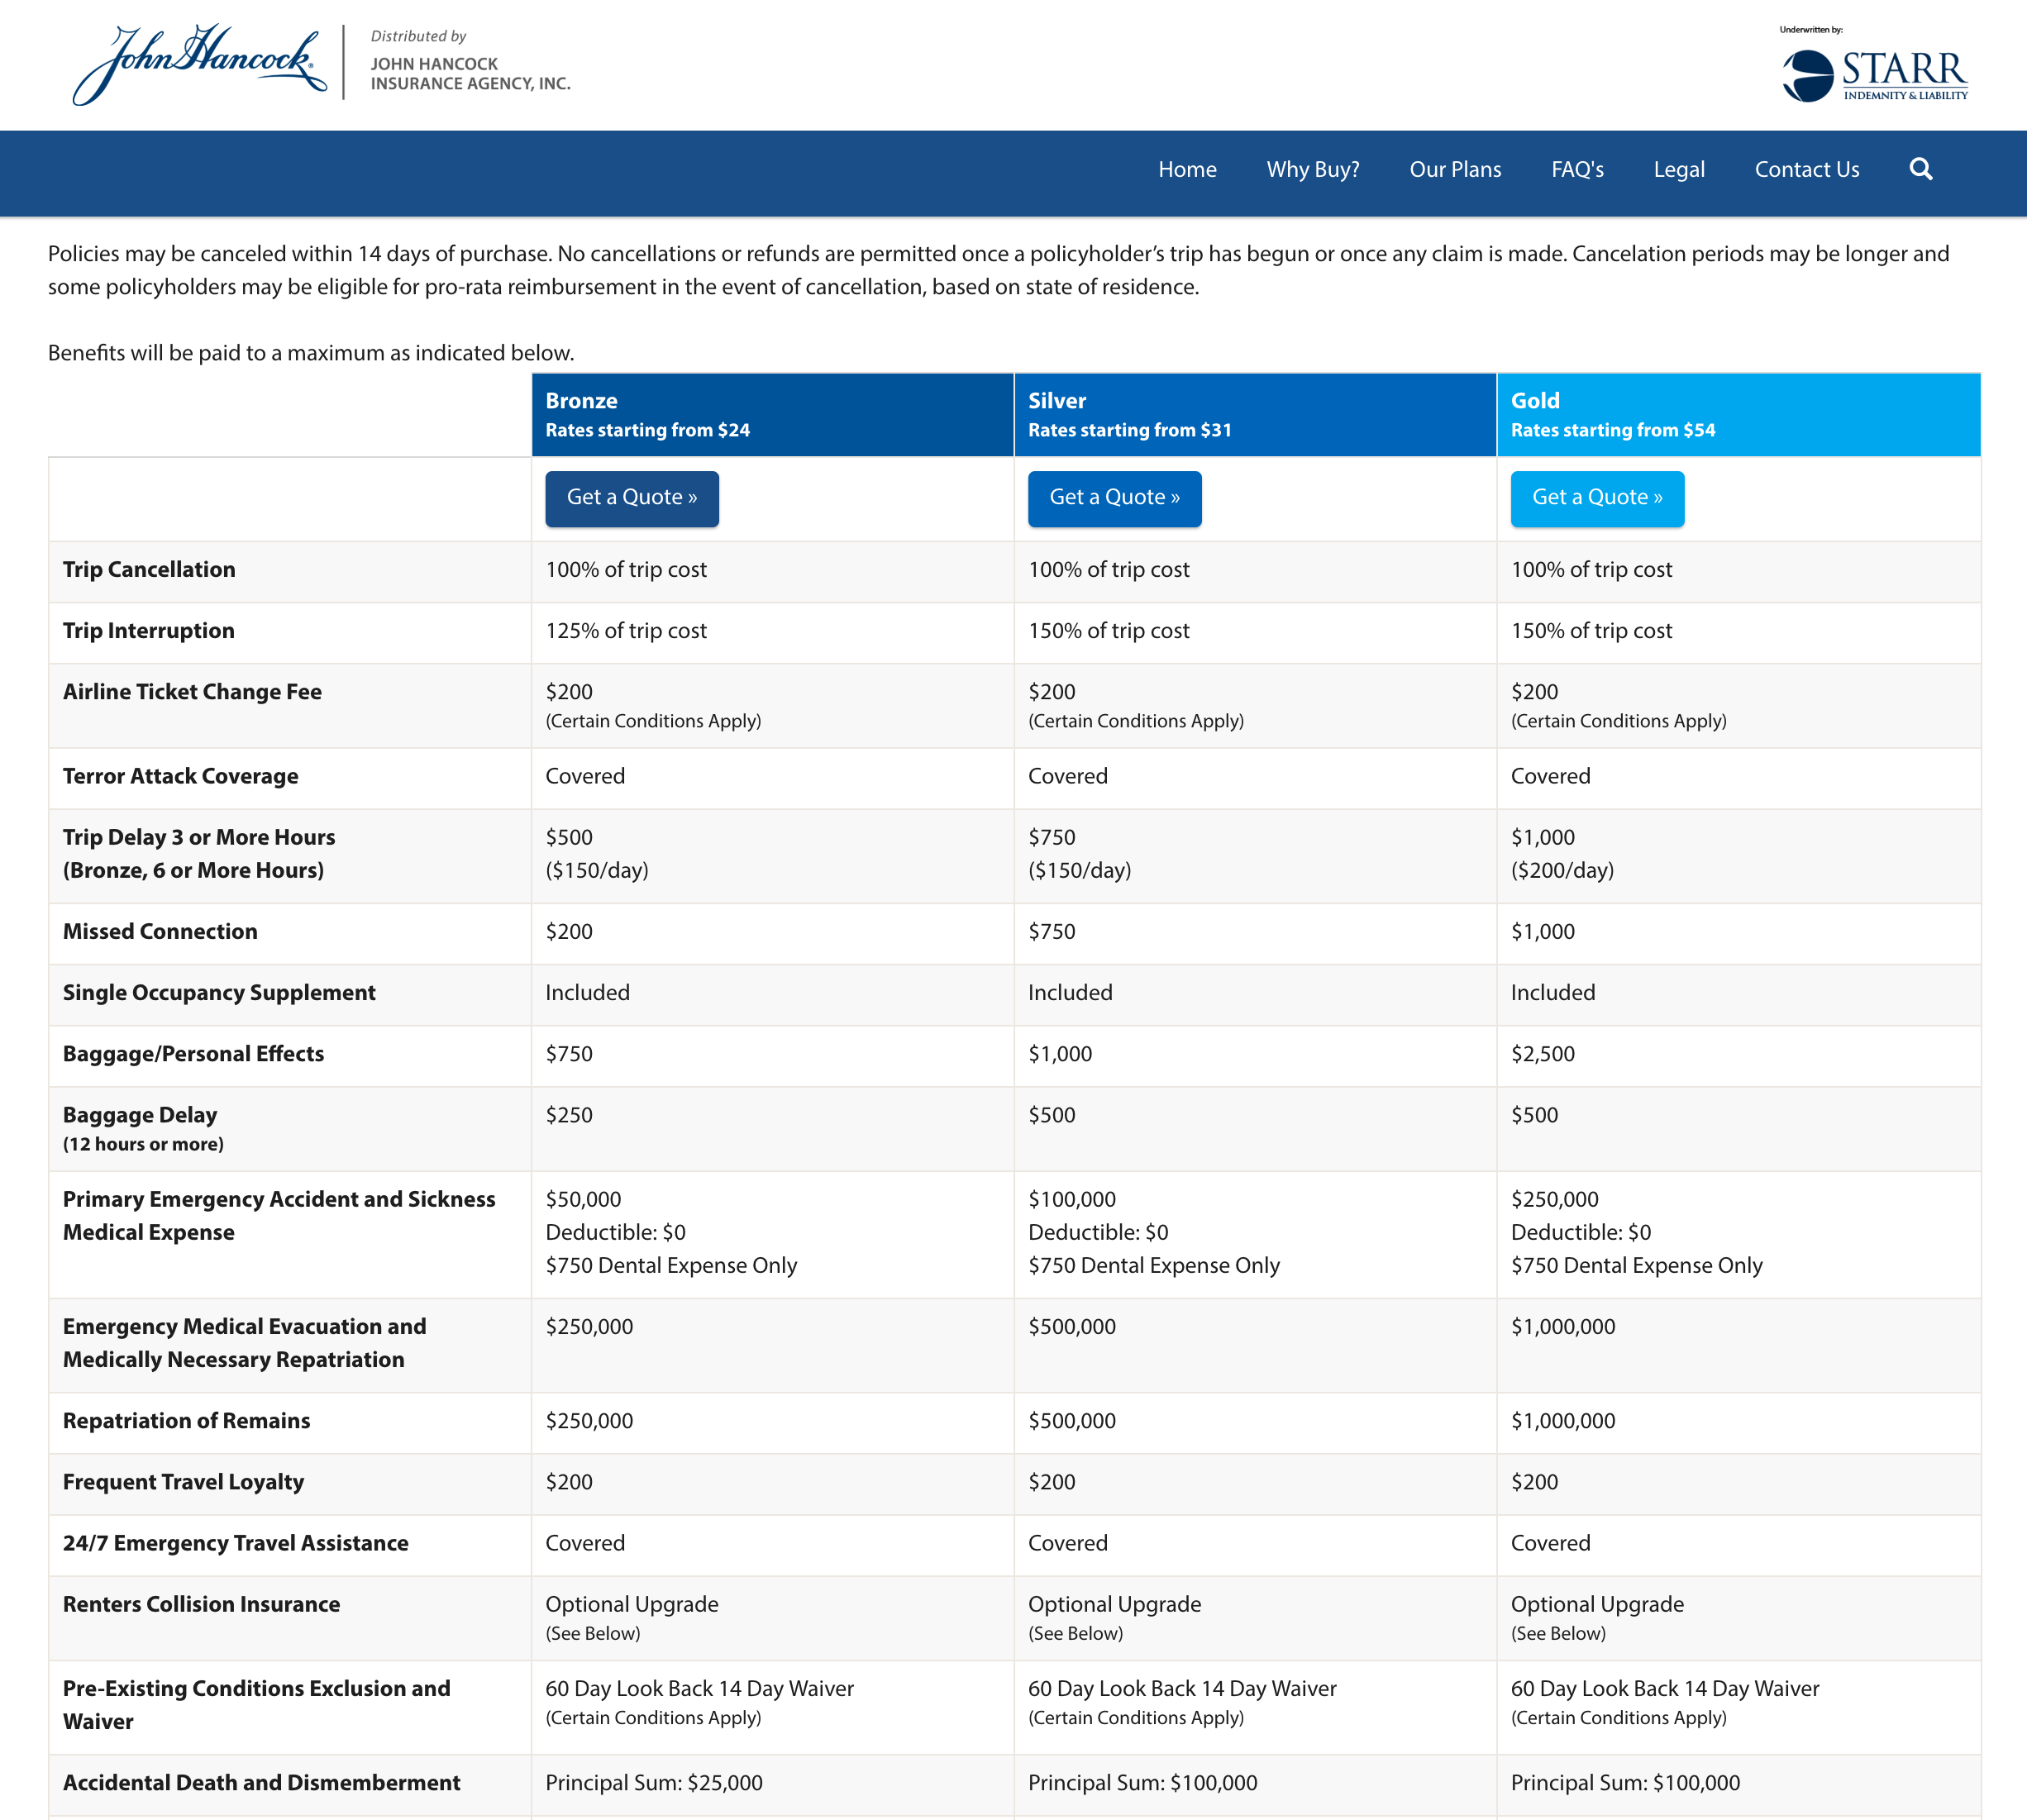
    Trip Cancellation Reimburses up to 100% of trip costs
    Emergency Medical Coverage up to $100,000
    Travel Delay $1,000 reimbursement potential
    Baggage Loss Up to $2,500 compensation

    These features ensure you’re not left stranded in case of any mishaps. Remember, peace of mind is just a policy away.

    Coverage and Benefits

    Ever wondered what would happen if your dream vacation turned into a nightmare due to unforeseen events? Here’s where John Hancock Gold Travel Insurance steps in, offering a safety net when you need it most.

    This insurance isn’t just about ticking a box; it’s about ensuring peace of mind wherever you go. From medical emergencies to trip cancellations, they’ve got you covered.

    Comprehensive Emergency Coverage

    Travel emergencies can happen to anyone, anywhere. With John Hancock Gold Travel Insurance, you’re protected against a wide range of scenarios. Imagine landing in a foreign country only to find your luggage has vanished. Or worse, you find yourself needing urgent medical care abroad. This plan has you covered in both cases and more.

    The policy provides coverage for:

    • Emergency medical and dental expenses
    • Trip cancellation or interruption
    • Lost, stolen, or damaged baggage
    • Emergency evacuation and repatriation
    • Travel delay and missed connection

    Real-Life Scenarios Highlighting Coverage Benefits

    Let’s paint a picture: You’re hiking in the Alps, and you twist your ankle. Or you’re on a safari, and your flight home gets delayed by a storm. In both scenarios, John Hancock Gold steps in to ease your stress. It covers medical treatment and helps manage the unexpected costs of rescheduling your flight.

    Pro Tip: Always read the fine print. Knowing what’s covered can save you from headaches later.

    Medical Coverage Limits Explained

    One of the most critical aspects of travel insurance is understanding your medical coverage limits. John Hancock Gold offers substantial coverage, ensuring you won’t be left with a hefty bill if you need medical attention abroad. The coverage limit for emergency medical expenses is generous, often going up to hundreds of thousands.

    Here’s how the policy breaks down:

    Benefit Coverage Limit
    Emergency Medical Expenses Up to $250,000
    Emergency Dental Up to $1,000

    Eligibility and Requirements

    Are you considering John Hancock Gold Travel Insurance for your next big adventure? Before you sign on the dotted line, let’s break down the eligibility criteria you need to meet.

    Understanding these prerequisites can save you time and ensure you’re fully prepared. After all, you wouldn’t want to miss out on coverage because of a simple oversight.

    Who Can Apply for John Hancock Gold Travel Insurance

    First, let’s talk about basic eligibility. To qualify, you must be a resident in a state where the policy is sold. BUT, there’s more to it. You also need to be traveling outside your home country for coverage to kick in.

    Now, here is the deal: the policy is designed to cover trips with a maximum duration, typically around 45 days. If your trip is longer, you’ll need to look at other options.

    Prerequisites for Coverage

    Before you get coverage, there are a few prerequisites you need to know. You must purchase the insurance before leaving on your trip. This seems obvious, right? BUT, you’d be surprised how often people overlook this!

    Also, you should ensure that your trip starts and ends in the same country. This is key to securing your coverage.

    Age Restrictions for Policyholders

    Age can be a factor with John Hancock Gold Travel Insurance. Typically, there are age brackets that determine premium costs. However, most age groups are eligible for coverage. BUT, if you’re over 80, the rates may be higher.

    Another point to keep in mind is that some benefits might be reduced if you’re in a higher age bracket. So, always read the fine print!

    Pro Tip: Review the age-specific policy terms to avoid any surprises later.

    Documents Needed for Obtaining Insurance

    Getting your documents in order is crucial for a smooth application process. Here’s a list of what you’ll need:

    • Valid Passport
    • Proof of Residency
    • Travel Itinerary
    • Payment Information
    • Any Pre-existing Medical Condition Forms, if applicable

    Make sure these documents are up-to-date and ready to go when you apply. This will help prevent any delays in processing your insurance.

    Cost and Pricing

    Explore John Hancock Travel Insurance Options

    Did you know that travel insurance is often overlooked, yet it’s crucial for your peace of mind when traveling? When it comes to John Hancock Gold Travel Insurance, understanding the pricing can be the difference between breaking the bank or saving a bundle on your next trip.

    Let’s break it down. Travel insurance premiums aren’t just pulled out of thin air. They depend on a few key factors that can significantly affect the bottom line.

    Comparing Pricing Tiers

    When you stack John Hancock Gold Travel Insurance against its competitors, you’ll notice that it’s not always the cheapest, BUT it packs a punch with its comprehensive coverage. Price isn’t everything when it comes to protecting yourself abroad. Many policies might seem affordable but lack the depth of coverage you’d expect.

    For instance, a typical premium might cost you around $150 for a week’s trip to Europe, whereas a less comprehensive plan could be $100. But here’s the deal: the cheaper plan might not cover medical evacuation or trip cancellation, which could leave you high and dry.

    Pro Tip: Always match the plan’s benefits with your travel needs before making a decision.

    Factors Influencing Premium Costs

    The cost of your travel insurance premium isn’t set in stone. It’s influenced by several factors like your age, the duration of your trip, and your destination. An older traveler or a longer trip equals a higher premium, plain and simple. But consider this: the destination can also drive up costs. Heading to a remote area? Expect to pay more due to increased risk and logistical challenges.

    Pricing Variations Based on Destinations

    Traveling to different parts of the globe can change your insurance premium significantly. Let’s say you’re planning a trip to Southeast Asia versus a European city break. The latter might be pricier due to the higher medical cost potential in Europe.

    Here’s a quick comparison using a hypothetical scenario:

    Destination Duration Age Group Premium Cost
    Europe 2 weeks 30-40 $200
    Asia 2 weeks 30-40 $150
    South America 2 weeks 30-40 $170

    Claim Process

    Ever wonder how seamless filing a claim with John Hancock Gold Travel Insurance could be? You might be shocked to find it’s easier than you think!

    Let’s dive into the step-by-step process to make sure you get what’s rightfully yours without the hassle. It starts with knowing the right steps and having the right documents at your fingertips.

    Steps to File a Claim

    Filing a claim doesn’t have to be a headache. Here is the deal: Follow these steps to ensure a smooth process:

    1. Step #1: Notify John Hancock ASAP. This means the moment something goes awry during your travels, reach out to them. The sooner, the better!
    2. Step #2: Fill out the claim form. You can find this on their website or request one via email.
    3. Step #3: Gather your documents. And I mean all of them: receipts, police reports, medical records, you name it.
    4. Step #4: Submit everything together. Make sure nothing is missing to avoid delays.
    5. Step #5: Follow up. Keep in touch with their claims department to stay updated.

    Documentation Required

    Documentation is key, and without it, you’re in for a rocky road. Here’s what you’ll need:

    • Completed claim form
    • Proof of travel (like tickets or itineraries)
    • Receipts for expenses
    • Medical reports if applicable
    • Police reports in case of theft or loss

    Pro Tip: Always make copies of your documents before submitting them.

    Expected Response Times

    Waiting is the worst part, right? But John Hancock promises swift action. Here’s how the timeline generally looks:

    Action Expected Time
    Initial Acknowledgment Within 48 hours
    Claim Assessment 5-7 business days
    Final Decision Within 14 business days

    Common Challenges

    Despite the process being straightforward, challenges can arise. BUT knowing them can help you dodge these bullets:

    • Incomplete documentation: This is the #1 reason for delays. Double-check before submission.
    • Misunderstanding coverage: Make sure you’re claiming for something your policy actually covers.
    • Delayed notifications: Waiting too long to report the incident can complicate things.

    Stay proactive, know your policy inside out, and you’ll have the edge in the claim game.

    Customer Reviews and Feedback
    Unlocking the Features and Benefits of John Hancock Gold Travel ...

    Did you know that 72% of customers say online reviews impact their purchasing decisions? When it comes to John Hancock Gold Travel Insurance, the feedback is crucial. Here’s what people are saying.

    Overall, customers are generally satisfied with the coverage provided. They appreciate the extensive options and the peace of mind it offers during travels. However, there are areas where users feel improvements could be made.

    Praises and Criticisms

    Many users rave about the comprehensive coverage that comes with the Gold plan. They love knowing that they’re protected against unexpected events, from flight cancellations to medical emergencies. But, here’s the deal: some users feel that the claim process is a bit lengthy. They mention that getting reimbursed can take longer than expected.

    Other common praises include the responsive customer service and the seamless online purchase experience. On the flip side, a few customers have reported confusion over policy details, which could be improved with clearer communication.

    Trends in User Satisfaction

    A trend that stands out is the high level of satisfaction with the medical coverage component. Many reviewers highlight how this aspect gives them confidence to travel without worries. But, some users note that understanding the full scope of benefits requires a deep dive into the policy documents.

    Moreover, younger travelers seem to appreciate the extra features like trip interruption and baggage coverage, valuing these as major stress relievers.

    “John Hancock’s Gold Travel Insurance saved my trip! When my flight got canceled, they had my back. Quick response, although the claim process took a bit more time than I’d hoped. Overall, I’d still recommend it for peace of mind.”

    Conclusion

    Unlocking the Features and Benefits of John Hancock Gold Travel ...

    In conclusion, John Hancock Gold Travel Insurance stands out as a top choice for travelers seeking reliability and comprehensive coverage. Its extensive benefits and straightforward claims process make it a favorite among globetrotters. So, whether you’re a seasoned traveler or planning your first big trip, consider this plan to safeguard your adventures and travel with confidence.

    Answers to Common Questions

    What are the primary benefits of John Hancock Gold Travel Insurance?

    This insurance provides extensive coverage for travel emergencies, including trip cancellations, lost luggage, and medical emergencies.

    How do I purchase John Hancock Gold Travel Insurance?

    You can acquire this insurance online through their website or by contacting a licensed insurance agent.

    What kinds of travel emergencies are covered?

    The policy covers various emergencies such as medical issues, trip cancellations, and interruptions, as well as baggage loss or delay.

    Are there age restrictions for policyholders?

    Yes, there are age restrictions. It’s essential to review the policy details or consult an agent to understand the specifics.

    How does the claim process work?

    The claim process involves submitting a claim form along with necessary documentation. The insurance provider will then review and process the claim.

  • Three Essential Types of Small Business Insurance Commercial Ventures Need

    Picture this: You’ve built your small business from the ground up. The late nights, the hard decisions, the passion all coming together to create something truly special. But wait, what happens when the unexpected strikes? That’s where small business insurance steps in to be your safety net!

    In this guide, we’ll dive deep into the world of small business insurance, uncovering the must-have policies that will protect your business from financial turmoil. Whether you’re just getting started or looking to bolster your current setup, understanding these insurance essentials is key to safeguarding your entrepreneurial dream.

    Understanding Small Business Insurance

    three small business insurance commercial ideas - bad.theyoungdev.com

    Did you know that 40% of small businesses have no insurance? That’s a huge risk to take. Understanding small business insurance is crucial to protect your investment and keep your business afloat.

    Small business insurance is like a safety net for your company. It covers a wide range of potential risks that could otherwise devastate your business. From liability claims to property damage, having the right coverage can be the difference between staying above water and financial ruin.

    Types of Insurance Coverage for Small Businesses

    There are several types of insurance policies that small businesses typically need. General Liability Insurance protects against claims of bodily injury or property damage. Professional Liability Insurance, often called errors and omissions insurance, covers you if a client claims you made a mistake in the services you provided.

    • Commercial Property Insurance: Covers damage to your business property from events like fire or theft.
    • Workers’ Compensation Insurance: Protects your employees if they get injured or sick at work.
    • Business Interruption Insurance: Helps cover lost income if your business is forced to close temporarily due to a covered event.

    Potential Risks Covered by Small Business Insurance

    Small business insurance is designed to shield you from a multitude of risks. Natural disasters, lawsuits, and even employee injuries can be financially crippling. Insurance helps manage these risks by covering the associated costs.

    Here is the deal: without adequate coverage, a single lawsuit or disaster could wipe out your business savings. Don’t wait until it’s too late. Assess your risks and get the right coverage now.

    Pro Tip: Regularly review and update your insurance policies to ensure they match the evolving needs of your business.

    Key Components of Insurance Policies

    The Essential Guide to Three Small Business Insurance Commercial ...

    Did you know that 40% of small businesses never reopen after a disaster? That’s why understanding your insurance policy is crucial.

    Insurance policies can feel like a maze, but once you break them down, they’re not that complex. Let’s uncover the main components of a typical small business insurance policy.

    Main Components of a Small Business Insurance Policy

    First, there’s the premium — that’s what you pay the insurer to keep your coverage. Then, the coverage — this details what risks are protected, like property damage or liability.

    Each policy includes inclusions and exclusions. For instance, while theft might be covered, flood damage often isn’t unless you have a specific add-on. That’s why reading the fine print is so crucial.

    Role of Deductibles and Coverage Limits

    Now, let’s talk about deductibles. This is the amount you pay out of pocket before your insurance steps in. Higher deductibles usually mean lower premiums. But here is the deal: set it too high, and you might risk financial strain.

    Coverage limits determine the maximum amount your insurer will pay. Choose wisely: underestimating can leave you vulnerable. Overestimating might mean unnecessary costs.

    Pro Tip: Always balance your deductible and premium for optimal financial protection.

    Three Essential Small Business Insurance Types

    Three Essential Small Business Insurance Commercial Insights - ris ...

    Did you know that 40% of small businesses have no insurance at all? That’s a huge risk! In today’s climate, having the right coverage can be the difference between thriving and surviving.

    Let’s dig into the three essential types of insurance every small business should consider. But these aren’t just any policies—each serves a specific need, keeping your business safe from the unexpected.

    General Liability Insurance

    General Liability Insurance is your first line of defense against common business risks. It covers third-party claims related to property damage, bodily injury, and personal injury. No business is immune to accidents, and this insurance ensures you’re not paying out of pocket for mishaps.

    Commercial Property Insurance

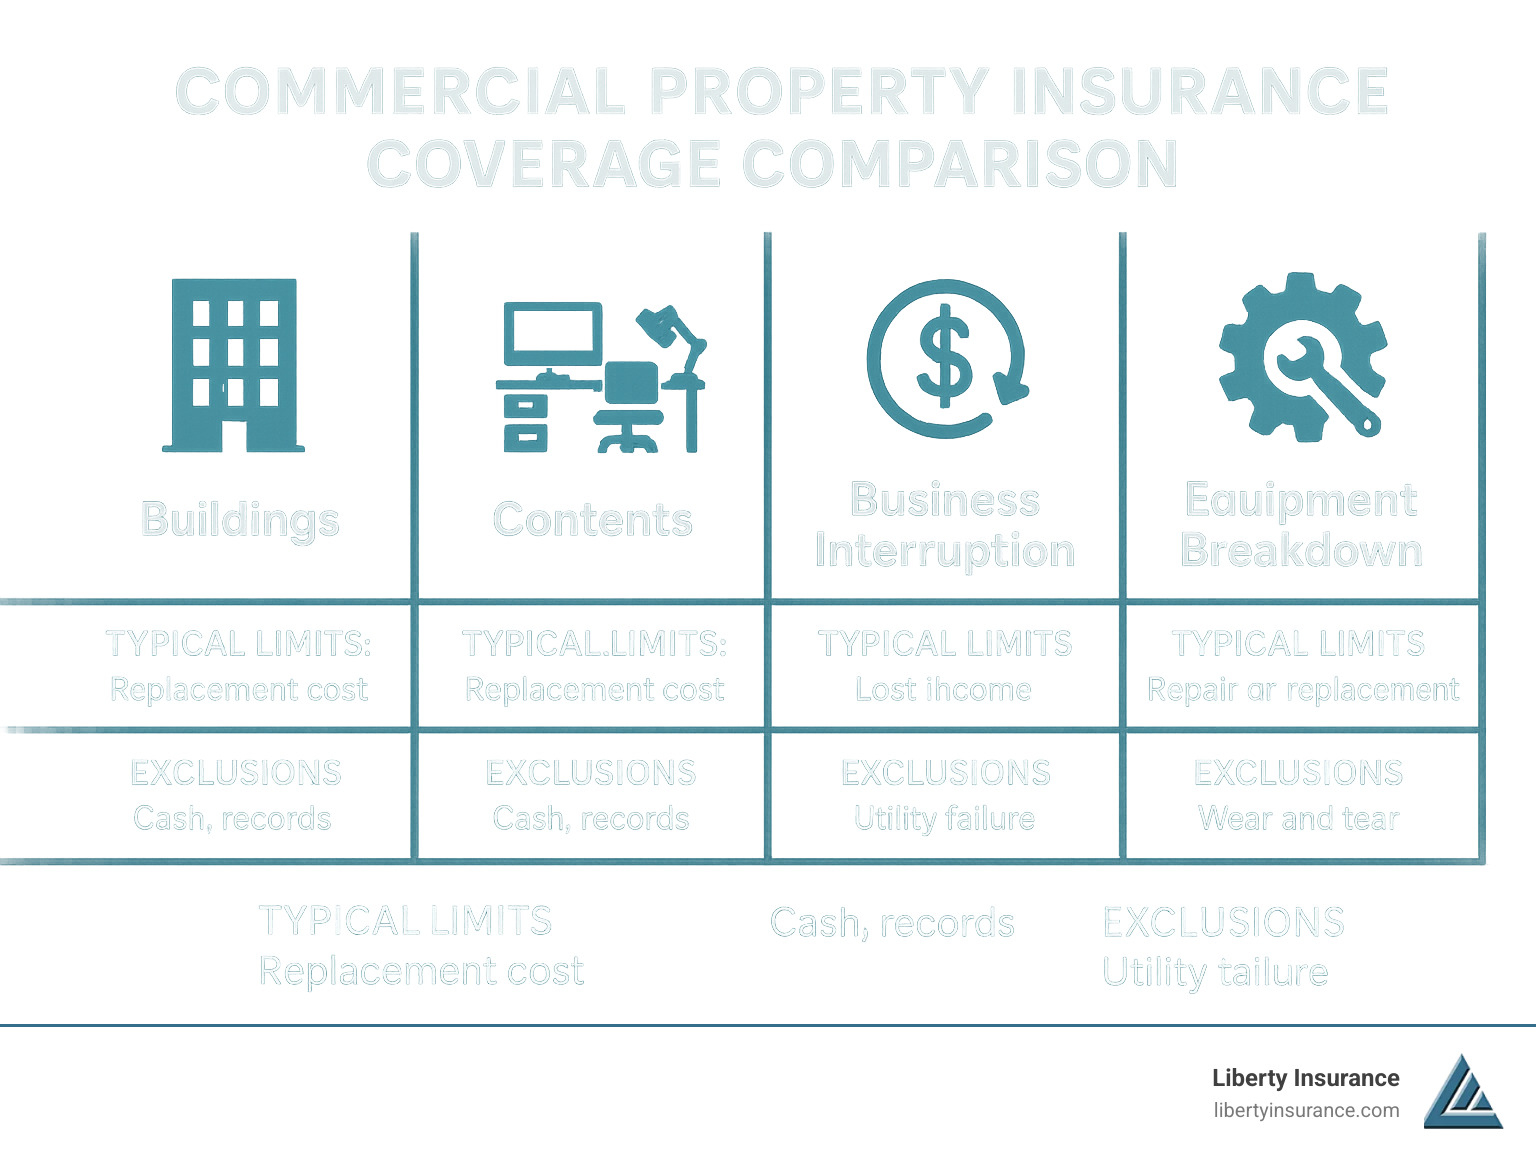
    What happens if a fire destroys your office? Commercial Property Insurance has got your back. This policy covers damage to your business property, including the building and its contents. It’s essential for businesses with physical assets they can’t afford to lose.

    Professional Liability Insurance

    Ever make a mistake that cost a client money? Professional Liability Insurance, also known as Errors and Omissions Insurance, covers lawsuits over professional mistakes. If your business offers services, this is a must-have to protect against claims of negligence.

    Here is the deal, these aren’t one-size-fits-all. Each has its own coverage, cost, and benefits. Let’s see how they stack up:

    Type Coverage Cost Benefits
    General Liability Third-party bodily injury and property damage $500-$1,000 annually Protects against lawsuits and claims
    Commercial Property Building and contents damage $750-$1,200 annually Secures physical assets against loss
    Professional Liability Negligence and errors claims $600-$1,800 annually Safeguards against service-related lawsuits

    Pro Tip: Bundle these policies for a discount and comprehensive coverage.

    Each type of insurance addresses a specific need. General Liability is ideal for customer-facing businesses, Commercial Property is crucial for those with physical locations, and Professional Liability is non-negotiable for service providers.

    Benefits of Commercial Insurance for Small Businesses

    Did you know that nearly 40% of small businesses never reopen after a disaster? Commercial insurance can be your financial lifeline. It’s crucial for safeguarding your livelihood.

    Without insurance, a single unfortunate event could wipe out your business overnight. But with the right coverage, you mitigate risks and fortify your business against financial storms. Let’s dive into how commercial insurance can make a difference.

    Financial Protection Against Unexpected Events

    Imagine your business facing a lawsuit, a fire, or even a natural disaster. These events can be devastating. Commercial insurance steps in to cover costs that could otherwise drain your assets. Not convinced? Consider this: 52% of small businesses experienced an insurance event in the past five years.

    Scenarios Where Commercial Insurance Can Save Your Business

    Picture this: a customer slips and falls on your premises. You could be facing hefty medical bills and legal fees. With liability insurance, you’re covered. Or what if a key piece of equipment breaks down? Equipment breakdown insurance can help you repair or replace it swiftly, avoiding prolonged business interruptions.

    Advantages of Adopting Commercial Insurance Across Business Sectors

    Here is the deal: different industries face different risks. But they all benefit from having robust insurance coverage. Let’s break down the advantages:

    • Retail: Protects against theft, property damage, and customer injuries.
    • Construction: Covers worker injuries and equipment damages on-site.
    • Food Service: Shields you from food spoilage, customer allergies, and kitchen accidents.
    • Tech Startups: Offers cyber liability protection and coverage for intellectual property theft.

    Avoid the financial pitfalls. Invest in commercial insurance to secure your business’s future.

    Selecting the Right Insurance Provider

    Did you know that over 40% of small businesses don’t have the right insurance coverage? That’s a risky gamble! Choosing the right insurance provider can make or break your business when disaster strikes.

    Here is the deal: you need to look beyond the premiums. A flashy price tag might catch your eye, BUT the real value lies in the coverage and services they offer. Let’s dive into the key factors you should focus on.

    Key Factors When Choosing an Insurance Provider

    You need more than just cheap rates. Consider the reputation of the provider. Are they known for honoring claims swiftly? Check their financial stability—you don’t want them folding when you need them most. Evaluate their customer service reviews. A company with 24/7 support is invaluable when an incident occurs at midnight.

    Pro Tip:

    Look for providers offering tailored policies for small businesses; generic policies might not cover your specific needs.

    Methods to Compare Insurance Providers

    Start by listing out potential providers. Then, head over to comparison websites, but take those ratings with a grain of salt. Instead, create a comparison table for a clearer picture:


    Provider Coverage Options Claim Processing Time Customer Reviews Price
    Provider A Comprehensive 48 Hours 4.5/5 $$$
    Provider B Basic 72 Hours 4.0/5 $$

    Checklist for Evaluating Potential Insurance Providers

    Before making a final decision, run through this checklist to ensure you’ve covered all bases:

    • Verify the provider’s licensing in your state.
    • Check for any complaints or legal actions against them.
    • Request a sample policy to review the fine print.
    • Ask about available discounts for bundling policies.
    • Inquire about their process for filing and managing claims.

    Ensuring you’re well-covered means doing your homework. With these steps, you’re on your way to making an informed choice that safeguards your business’s future.

    The Impact of Insurance on Business Continuity

    Did you know that 40% of businesses never reopen after a disaster? That’s a shocking stat. But with the right insurance, your business doesn’t have to be one of them.

    Insurance isn’t just a safety net; it’s a lifeline during unexpected challenges. When a crisis hits, having proper insurance coverage can mean the difference between closing your doors or bouncing back stronger than ever.

    Ensuring Business Continuity During Crises

    Here is the deal: business continuity hinges on preparedness. When disaster strikes, having comprehensive insurance can keep your operations running smoothly. Whether it’s a natural disaster, theft, or an unexpected lawsuit, your insurance policy can cover the financial gaps, allowing you to focus on getting back on your feet.

    Step #1: Review your insurance coverage regularly to ensure it matches your current business needs. Step #2: Establish a relationship with your insurer. Understanding your policy details can save you time and stress when filing a claim.

    The Process of Filing an Insurance Claim

    Filing an insurance claim during a crisis can be daunting. BUT, it doesn’t have to be. First, document everything. Take photos, gather receipts, and get a police report if necessary. Then, contact your insurer as soon as possible to start the claims process.

    Pro Tip:

    Keep a digital copy of all your important documents. Accessing them quickly can expedite your claim process.

    Once your claim is filed, follow up regularly to ensure it’s being processed promptly. Remember, your insurer is your partner in getting your business back on track.

    Success Stories: Bouncing Back with Effective Insurance Coverage

    Let’s look at businesses that thrived after crises. One restaurant, devastated by a fire, managed to reopen in just six months, thanks to their business interruption insurance. This coverage compensated for lost income during the rebuild.

    Another example is a retail store that rebounded from a major flood. Their comprehensive policy covered both property damage and stock replacement, allowing them to resume operations with minimal delay.

    These stories aren’t just luck. They’re a testament to the transformative power of having the right insurance at the right time.

    Last Word

    In the grand scheme of business strategy, insurance might not feel like the most thrilling aspect, but it’s undeniably crucial. By securing the right coverage, you’re not just protecting your assets; you’re ensuring your business’s longevity and stability. Remember, it’s better to have insurance and not need it than to need it and not have it. Here’s to a safer, more secure business future!

    Frequently Asked Questions

    What are the three essential types of small business insurance?

    The three essential types are General Liability Insurance, Professional Liability Insurance, and Commercial Property Insurance.

    Why is General Liability Insurance important for small businesses?

    General Liability Insurance protects your business from claims related to bodily injury, property damage, and advertising injury, making it a fundamental coverage for any business.

    How does Professional Liability Insurance benefit a service-based business?

    This insurance covers claims of negligence, errors, or omissions in the services you provide, crucial for businesses where expertise and advice are offered.

    What does Commercial Property Insurance cover?

    Commercial Property Insurance covers damage to your business’s physical assets, such as buildings and equipment, from risks like fire, theft, and natural disasters.

    How can I choose the right insurance provider for my small business?

    Consider factors like the provider’s reputation, financial stability, coverage options, and customer service. Comparing multiple quotes is also advisable.