Finding the best insurance rates in NC can feel like searching for a needle in a haystack. With so many options and variables to consider, it’s easy to get overwhelmed. But don’t worry, we’ve got you covered! In this guide, we break down the essential tips and tricks to help you navigate the insurance landscape in North Carolina.
From understanding the different types of insurance available to learning how to negotiate better premiums, we’ve compiled all the insider knowledge you need to make informed decisions. So buckle up and get ready to become an insurance savvy shopper!
Understanding Insurance Types in NC
Did you know that North Carolina ranks among the top states for its diverse insurance options? If you’re living in NC, understanding your insurance options isn’t just helpful—it’s crucial.
Whether you’re insuring your car, your home, your health, or your life, you need to know the specifics. Let’s dive into the different insurance types available in North Carolina and how they stack up against each other.
Auto Insurance in North Carolina
North Carolina mandates that all drivers carry liability insurance. This covers bodily injury and property damage. But, there’s more than just the legal minimum. Consider comprehensive and collision coverage, which provide broader protection. With NC’s population density increasing, having adequate auto insurance is essential to protecting yourself on the road.
Home Insurance Essentials
Homeowner’s insurance in North Carolina is crucial due to the state’s exposure to hurricanes. You need coverage that protects against wind and flood damage. BUT, don’t forget about the standard protection for fire, theft, and vandalism. Home insurance rates can vary dramatically depending on location and home value.
Health Insurance Options
In North Carolina, health insurance comes in many forms, from employer-sponsored plans to private options through the ACA marketplace. The key here is to understand the difference between HMO, PPO, and High Deductible plans. Each has its pros and cons depending on your healthcare needs and financial situation.
Life Insurance: Securing Your Future
Life insurance is the ultimate safety net for your loved ones. In North Carolina, you have term life and whole life options. BUT, which one suits you better? Term life is generally more affordable but expires after a set period. Whole life is more expensive but offers lifelong coverage and a cash value component.
Comparing Insurance Types
To make an informed decision, you need to compare the different types of coverage side by side. Here’s a quick reference table:
| Insurance Type | Coverage Details | Typical Rates |
|---|---|---|
| Auto Insurance | Liability, Comprehensive, Collision | $600 – $1,500/year |
| Home Insurance | Fire, Theft, Wind, Flood | $800 – $2,000/year |
| Health Insurance | HMO, PPO, High Deductible | $300 – $600/month |
| Life Insurance | Term, Whole Life | $30 – $200/month |
Pro Tip: Always review your insurance policy annually to ensure it still meets your needs.
Factors Affecting Insurance Rates in NC
Did you know that where you live in North Carolina can make your insurance rates skyrocket? That’s right. It’s not just your driving record or credit score that insurers are looking at.
When it comes to insurance premiums in North Carolina, several key factors come into play. Understanding these can arm you with the knowledge to get the best rates possible.
Location’s Impact on Insurance Premiums
Believe it or not, your zip code could be costing you hundreds of dollars in insurance each year. Urban areas like Charlotte and Raleigh tend to have higher premiums. This is because these areas often have a higher rate of accidents and theft compared to rural areas. BUT, living in a less populated area might not always guarantee lower rates, especially if the area has a history of natural disasters like hurricanes.
Credit Scores and Driving History Table
Here’s the deal: Your credit score and driving history are two major factors that insurers consider. They can significantly impact your insurance costs, sometimes more than your location. Let’s break it down:
| Factor | Impact on Insurance Costs |
|---|---|
| Credit Score: Excellent | Lower premiums due to perceived lower risk |
| Credit Score: Poor | Higher premiums as a higher risk is assumed |
| Driving History: Clean | Lower rates with potential discounts |
| Driving History: Multiple Accidents or Violations | Significantly higher premiums due to increased risk |
Pro Tip: Improving your credit score and maintaining a clean driving record can save you a substantial amount on your insurance premiums!
Top Insurance Providers in NC

Did you know that over 90% of North Carolinians have some form of insurance coverage? But not all insurance providers are created equal.
Finding the right insurance company can feel like searching for a needle in a haystack. Here’s the deal: I’ve narrowed it down to the top providers in North Carolina, each offering unique perks and excellent services. Let’s dive in.
Leading Insurance Companies Operating in North Carolina
In North Carolina, the insurance landscape is dominated by a few key players. These companies not only offer comprehensive coverage but are also known for their exceptional customer service.
- State Farm: Known for its robust auto and home insurance policies, State Farm also offers a convenient mobile app for policy management.
- Nationwide: Offers a variety of coverage options and is famous for its customer-first approach, especially in home and life insurance.
- Blue Cross Blue Shield of NC: A top choice for health insurance, offering a wide network of providers and competitive rates.
- GEICO: Competitive auto insurance rates and a user-friendly online platform make GEICO a popular choice.
- Progressive: Offers unique perks like the Name Your Price tool, which allows you to customize your premium based on your budget.
Services and Perks Offered by Each Provider
Each insurance provider offers a distinct set of services and perks that can make a big difference in your experience. Here’s a closer look:
- State Farm: Multiple policy discounts, 24/7 customer support, and a highly-rated claims process.
- Nationwide: Vanishing deductible program and free annual insurance reviews.
- Blue Cross Blue Shield of NC: Comprehensive health plans with wellness discounts and virtual care options.
- GEICO: Emergency roadside assistance and accident forgiveness features.
- Progressive: Snapshot program for usage-based insurance savings and pet injury coverage in auto policies.
Comparison of Customer Satisfaction Ratings and Coverage Options
When choosing an insurance provider, it’s crucial to consider both customer satisfaction and coverage options. Here’s how the top players stack up:
| Provider | Customer Satisfaction Rating | Coverage Options |
|---|---|---|
| State Farm | 4.5/5 | Auto, Home, Life, Renters |
| Nationwide | 4.3/5 | Auto, Home, Life, Specialty |
| Blue Cross Blue Shield of NC | 4.2/5 | Health, Dental, Vision |
| GEICO | 4.4/5 | Auto, Motorcycle, RV, Boat |
| Progressive | 4.1/5 | Auto, Home, Renters, Pet |
Pro Tip: Before you commit, reach out to these providers for personalized quotes. It’s amazing how much you can save by just asking!
Tips for Finding the Best Insurance Rates
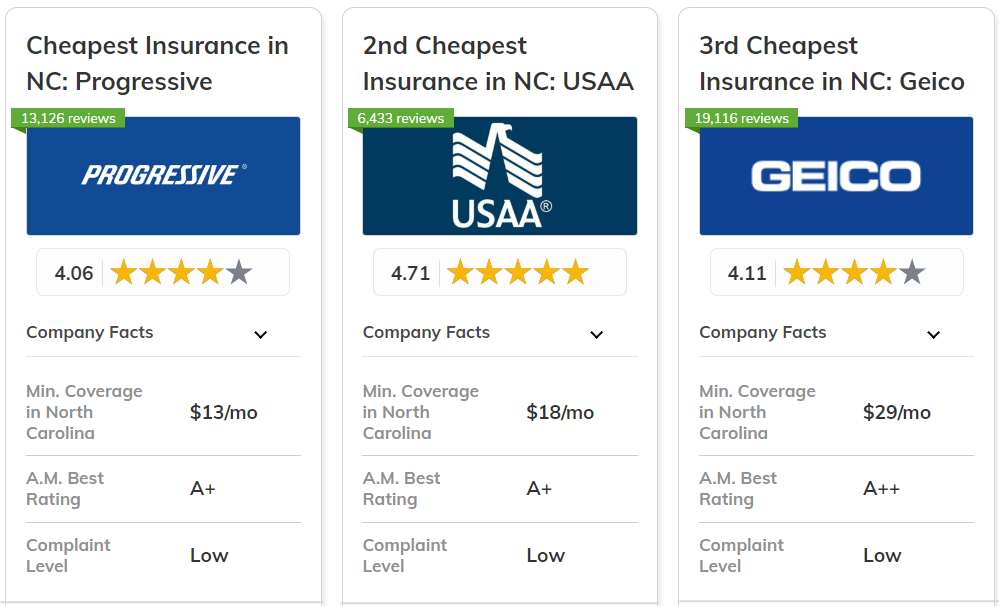
Did you know that over 70% of people in NC could be overpaying on their insurance? If you’re one of them, it’s time to take action! Finding the best insurance rates doesn’t have to be a chore. A few smart strategies can save you hundreds, maybe thousands, each year.
Let’s break down what you need to do to snag those sweet, wallet-friendly rates. From comparing rates like a pro to bundling your policies, these tips will turn you into an insurance-savvy shopper in no time.
Effective Strategies for Shopping and Comparing Insurance Rates
Shopping around is crucial. Not all insurance policies are created equal, and neither are their prices. You might find the same coverage at drastically different costs from different providers. Here’s the deal: use comparison tools and quote aggregators to gather data from multiple insurers. These tools are your lifeline to understanding the competitive landscape.
Pro Tip: Use at least three different comparison websites to ensure you’re not missing out on any hidden gems.
But don’t stop there! Call the companies directly. Sometimes, speaking to a representative can unlock discounts that online tools miss. An extra 5-10% off just for chatting? Yes, please!
Benefits of Bundling Different Insurance Policies
Ever heard of the saying, “Don’t put all your eggs in one basket”? Well, that doesn’t apply here. Bundling your insurance policies can lead to significant discounts. Insurers love when you bring them more business, and they’ll reward you for it. Combine your auto, home, and even life insurance to get the best discounts.
But here’s the kicker: while bundling can save you money, it’s essential to ensure you’re not compromising on coverage quality. Always review the terms and conditions. No point in saving money if you’re left high and dry when you need to file a claim.
Methods to Negotiate Better Insurance Premiums with Providers
Think you can’t negotiate insurance premiums? Think again. While most people accept the first offer, there’s often room to haggle. Start by researching average rates for your coverage in NC. Armed with this info, you can approach your provider and discuss potential reductions.
Don’t shy away from asking about discounts you might qualify for. Safe driver discounts, no-claims bonuses, and membership perks are just a few examples. If a competitor offers a better rate, mention it. Insurers hate losing customers and might match or beat those rates.
Remember, the key is to stay informed and proactive. Insurance companies won’t hand you savings on a silver platter; you have to ask for it!
Understanding Policy Details and Exclusions
Ever wondered why your insurance claim got denied? It might be lurking in the fine print. Understanding policy details and exclusions is crucial if you want to avoid any nasty surprises down the road.
Let’s face it. Insurance policies can be a labyrinth of legal jargon and hidden clauses. BUT, knowing the common inclusions and exclusions can save you from potential headaches and financial loss.
Common Policy Inclusions and Exclusions in NC
Insurance policies in North Carolina often include basic coverage options like liability and protection against specific perils. However, exclusions are where things get tricky. For instance, many homeowners’ policies exclude flood damage, which means you’d need separate flood insurance.
- Inclusion: Liability Coverage – protects against legal claims.
- Inclusion: Property Damage – covers damage to your property.
- Exclusion: Flood Damage – typically not covered under standard policies.
- Exclusion: Earthquake Damage – usually requires an add-on policy.
Here is the deal: You need to grasp these terms before signing on the dotted line.
Critical Policy Terms to Understand
Before diving into a policy, make sure you understand these key terms. They can make or break your insurance coverage.
- Deductible: The amount you pay out of pocket before insurance kicks in.
- Premium: The cost you pay regularly to keep your policy active.
- Coverage Limit: The maximum amount your insurer will pay for a covered claim.
- Exclusion: Specific conditions or circumstances not covered by the policy.
Pro Tip: Always read policy documents carefully and ask your agent to clarify any confusing terms.
Policy Coverage Limits and Potential Exclusions
Different policies have various coverage limits and exclusions. It’s essential to compare these before making a decision.
| Policy Type | Coverage Limit | Exclusions |
|---|---|---|
| Homeowners | $300,000 | Flood, Earthquake |
| Auto | $100,000 per accident | Intentional damage |
| Health | Varies | Cosmetic procedures |
Understanding these details can empower you to choose the right policy that fits your needs.
Common Mistakes to Avoid When Buying Insurance in NC
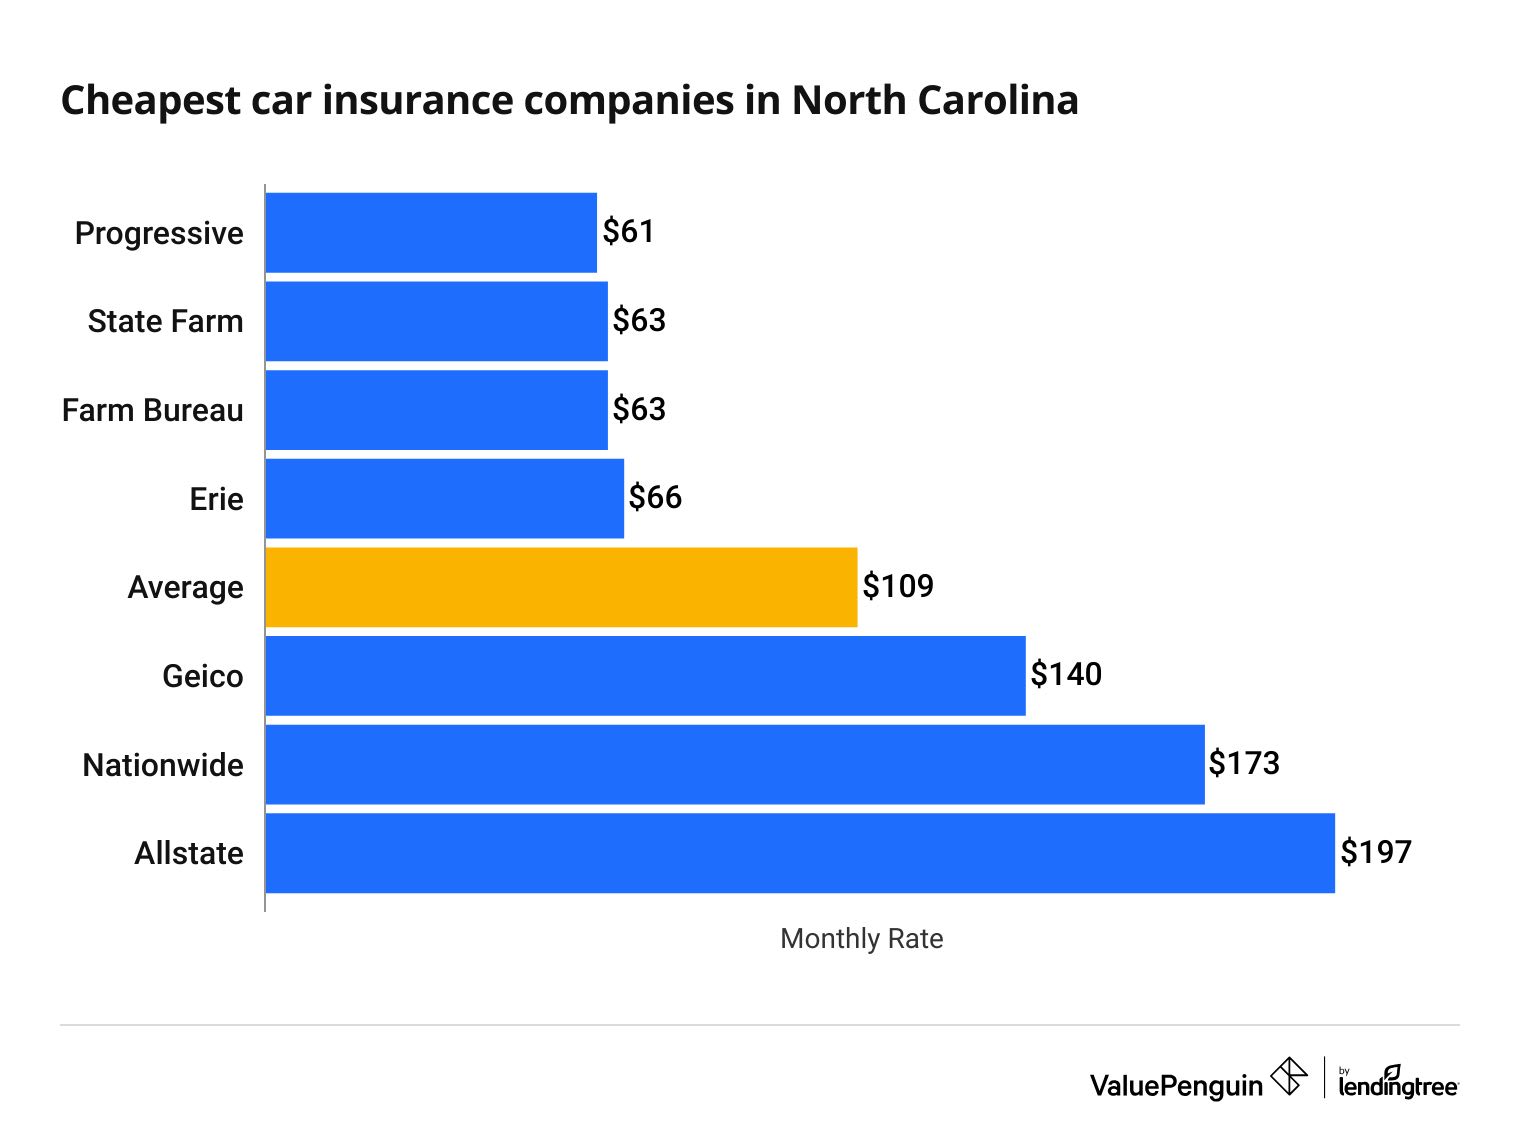
Think you’ve found the best insurance deal in NC? Think again. Many consumers make critical mistakes when choosing policies.
These errors can lead to being either underinsured or overinsured, costing you time and money. But don’t worry. I’m here to help you navigate this insurance minefield.
Overlooking Comprehensive Coverage
When you’re hunting for insurance, it’s easy to just focus on the price. But here’s the deal: opting for the cheapest policy can leave you underprotected. It’s like buying a car without seatbelts just because it’s cheaper.
To avoid this mistake, always analyze what each policy covers. Make sure it aligns with your unique needs.
“I thought I had storm damage coverage. After a hurricane hit, I found out otherwise. Huge mistake!” – North Carolina resident
Not Understanding Policy Limits
Policy limits are crucial. They dictate how much your insurer will pay out in the event of a claim. If you don’t pay attention, you could find yourself paying out of pocket for expenses above your limits.
Pro Tip: Always match your policy limits with potential real-world scenarios. Consider the worst-case scenario and plan accordingly.
Ignoring Deductibles
Sure, a low premium feels nice on the wallet. BUT, if your deductible is sky-high, it could come back to bite you when you file a claim. A higher deductible means more out-of-pocket costs before your insurance kicks in.
Balance is key. Find a deductible that keeps premiums low, but won’t bankrupt you during a claim.
Skipping Regular Policy Reviews
Life changes. So should your insurance. Yet, many people forget to update their policies when significant life events occur, like buying a home or having a child.
Review your policy annually. Confirm it still meets your needs and adjust your coverage accordingly. Trust me, future you will be grateful.
Conclusion
There you have it—your complete roadmap to securing the best insurance rates in NC. With the right strategies and insights, you can master the art of finding great deals and ensuring your coverage fits your needs perfectly. Remember, knowledge is power, and now you’re fully equipped to tackle the insurance world with confidence.
Common Queries
What are the main types of insurance available in NC?
In North Carolina, you can find auto, home, health, and life insurance as the primary types of coverage.
How can my location in NC affect my insurance rates?
Your location can significantly impact your insurance premiums due to factors like crime rates, weather patterns, and local regulations.
Why is my credit score important for insurance rates in NC?
Insurance companies often use credit scores to assess risk, influencing the rates they offer you.
Can bundling insurance policies really save me money?
Yes, bundling multiple policies with the same provider often results in discounts and savings on your overall insurance costs.
What are common mistakes to avoid when buying insurance in NC?
Avoid being underinsured or overinsured by carefully reviewing your coverage needs and understanding policy details and exclusions.